Resources
How the Plaintiff Recovery Trust Can Help E. Jean Carroll and Others
After the plaintiff double tax reduces her settlement, E. Jean Carroll may find herself shopping at Walmart.
As you may know, E. Jean Carroll was recently awarded $83 million in her defamation case against former President Donald J. Trump. After the case Ms. Carroll quipped to Rachel Maddow on MSNBC, “I have such great ideas for all the good I'm going to do with this money”.
“First thing Rachel, you and I are going to go shopping at Bergdorf’s.”
But wait, there is the double tax bite. As all of Ms. Carroll's settlement proceeds are taxable, It is therefore subject to the plaintiff's “double tax” under the Supreme Court's banks taxation ruling. Thus, if her attorney receives a typical 40% contingency fee, then, of the $83 million, she will only end up with approximately $7.5 million; just nine cents on the dollar. Even if her award is reduced on appeal, the same double taxation treatment applies.
The good news is that the Plaintiff Recovery Trust, sponsored by Eastern Point Trust Company and Forward Giving, can eliminate the double tax burden. It does so by eliminating the plaintiff's requirement to pay tax on the attorney fee portion of the settlement, thereby materially increasing the plaintiff's net after-tax proceeds.
Contact Eastern Point to learn how the Plaintiff Recovery Trust may increase your after tax recovery up to 150%.
Why Qualified Settlement Funds Are a Valuable Tax and Financial Planning Tool in Personal Injury Cases
When confronted with resolving a personal injury case, whether or not involving a client reliant on public assistance, intricate issues such as the allocation of proceeds, settlement planning, and lien negotiations must be meticulously managed. One critical question arises: where can the settlement funds be temporarily held while establishing any requisite public benefit preservation trusts, determining the distribution of proceeds, devising a comprehensive financial plan, and finalizing lien negotiations? How can one secure immediate payment from the defendant without compromising the client’s potential settlement planning strategies?
The solution to these complex challenges lies in utilizing a Qualified Settlement Fund (QSF), also known as a 468B Trust. Continue reading to gain a deeper insight into QSFs and understand why they are essential for personal injury attorneys to master.
What Is a QSF
A Qualified Settlement Fund is a provisional trust (think of it as “tax limbo”) established to manage the settlement funds received from one or more defendants. The primary function of a QSF is to distribute the deposited funds to multiple claimants pursuant to the parties’ agreement or, if necessary, a court order. The QSF termination occurs once all the funds are vested and distributed.
There are several benefits to utilizing a QSF in complex settlements. Chief among them is the simplicity of its establishment. There are only three stipulations for forming a QSF. First, the QSF has approval requirements from a “governmental authority” with jurisdiction over the QSF. Second, the QSF must settle only tort claims or other legal disputes as outlined by Treasury regulations 1.468B-1, et seq. Finally, if established as a trust, it must qualify as such under relevant state law. Any “governmental authority,” irrespective of its jurisdiction over the case, can approve the establishment of the QSF and maintain continuing oversight of the QSF.
Qualified Settlement Funds are a provisional repository for litigation and settlement proceeds. Its purpose is not to function as a perpetual support trust for claimants. Instead, the QSF remains operative only until all allocation disputes among parties and third-party liens are complete and the necessary planning for fund distribution is final. This duration can sometimes extend from several weeks to months or even years.
PRO TIP: No predefined time constraint exists on how long a QSF can remain active. Using a QSF to serve as a long-term tax deferral vehicle is improper. The best practice is that a QSF should remain open no more than 12 calendar months beyond resolving all secondary issues and disputes.
QSFs provide numerous advantages for all involved parties, particularly concerning tax implications, income timing, and settlement planning requirements. A QSF allows for establishing a tax-exempt structured settlement and a tax-deferred arrangement for attorney fees. The management of income timing is possible with a QSF. Generally, claimants are not taxed on the amounts held within the QSF until those amounts are vested by the trustee and disbursed. Additionally, a QSF affords claimants additional time and flexibility (through tax deferral) to make informed decisions regarding their tax, financial planning, and settlement planning strategies.
Benefits of a Qualified Settlement Fund
The benefits for a defendant are that transferring the associated proceeds into the QSF results in an immediate tax deduction in exchange for their permanent release from the obligation. This benefit is significant for defendants, who usually cannot claim a deduction until the claimant receives the funds, which can be postponed in complex settlements.
PRO TIP: Note that the timing of distributions to the claimants from the QSF does not affect the defendant’s ability to claim this tax deduction concurrently upon the transfer.
For the plaintiff, the benefits are the advantage of unrushed additional time to explore tax and financial planning options and resolve liens and other types of secondary disputes. This benefit is significant for plaintiffs, as valuable tax and financial options would otherwise not be available.
QSF Structure
The tax structure for Qualified Settlement Funds is straightforward. Each QSF is assigned a unique Employer Identification Number (EIN) by the Internal Revenue Service. QSFs are subject to taxation based on their modified gross income, excluding the monetary settlement or award receipts, and the corporate income tax rate applies only to the “investment income” of the QSF. Consequently, the tax obligation pertains to the growth of the principal amount through interest or dividends minus permissible deductions such as administrative expenses.
Internal Revenue Code §468B, alongside the Income Tax Regulations articulated in §1.468B-1, et seq., governs the application of a Qualified Settlement Fund. These statutes stipulate that a defendant may execute a qualifying payment to the QSF, thereby achieving “economic performance” — a critical tax consideration for the defendant. Consequently, the trustee of the QSF is empowered to accept settlement funds, enabling the defendant to claim a deduction for the current fiscal year and extricate themselves from litigation.
Post receipt of the settlement/litigation proceeds, the QSF trustee can consent to future periodic payments to a plaintiff, delegate this responsibility to a third entity by assignment or novation, and facilitate the plaintiff’s reception of tax-exempt payments under Internal Revenue Code §104(a) coupled with §130. This specific provision excludes structured settlement periodic payments from being counted as gross income in personal injury cases.
PRO TIP: If the settlement is paid into the law firm’s IOLTA, the plaintiff loses the ability to assign, novate, or structure. Likewise, the same loss of ability to enter into an attorney fee structure or assign occurs when funds are received into the IOLTA.
The Process of Utilizing a QSF
Establishing a QSF is a straightforward process in terms of procedural steps. Initially, the “governmental authority” is petitioned to form the QSF. The governmental authority receives the associated petition and documents and approves the establishment of the QSF. Upon the court’s approval and signing of the order, the defendant(s) issue the payment(s) to the QSF by wire or a check, and in exchange, the associated defendant receives a release from liability pertaining to the payment.
PRO TIP: A QSF’s records should document the payment into the QSF rather than directly to the plaintiff or the law firm.
The timing of distributions from a QSF is contingent upon either an agreement with the plaintiffs or an order by a court. When disbursing funds from the QSF, it is incumbent upon the trustee to secure a release from the claimants (or their agent), which serves as evidence that their claims against the QSF have been resolved or satisfied by the distribution. Upon the disbursement of all funds, the trustee terminates the QSF.

QSFs Mitigate the Settlement Time Pressure
QSFs are an essential resource for personal injury trial attorneys primarily because they speed up the process by mitigating the time pressures associated with lien negotiations, allocations, and probate processes.
The conclusion (whether by settlement or award) of a personal injury lawsuit often leads to a frenzied period to finalize details, a situation referred to as the “settlement pressure cooker.” In such hurried circumstances, one might overlook critical details, neglect vital settlement planning matters, trigger unnecessary accelerated taxation, or unfairly pressure the plaintiff to make hasty decisions.
Establishing a QSF enables the receipt of settlement funds, allowing sufficient time for meticulous future planning.
PRO TIP: Plaintiff counsel can promptly receive payment of the claimant’s attorney fees and costs obligations while allowing the plaintiff’s portion net of the plaintiff’s attorney fee obligations to remain in the QSF.
PRO TIP: The QSF is the sole owner of the funds and the associated income of the QSF (§468B(b)(c)(3)). Until the trustee vests a benefit, no claimant has any vested right. Further, the claimants may have a personal obligation to their attorneys for a portion of the settlement as fees, but that obligation vests no rights to the attorneys within the QSF. Therefore, attorneys have no greater standing than any other party that may have a general personal lien against a claimant. Thus, when the QSF makes payments to the attorneys, such payment is solely from the claimant’s proceeds for the administrative convenience of the claimant to fulfill the claimant’s personal obligation.
Once the defendant transfers “collected” funds into the QSF, the claimant may “petition the trustee” to vest and disburse funds subject to all other factors, such as allocation, the satisfaction of liens, resolution of secondary disputes, etc. This arrangement facilitates the negotiation of liens, determining fund allocations, implementing public benefit preservation trusts, and considering settlement planning issues, including structured settlements. Moreover, this mechanism preserves the attorney’s ability to assign or structure their fees. Consequently, the QSF is a valuable tool for trial attorneys to implement effective financial planning.
Conclusion
QSFs serve as a unique tool and valuable resource in personal injury cases by removing the post-settlement/litigation time pressures and affording flexible tax and financial planning options for the defendants, the plaintiffs, and the plaintiff lawyers, as well as facilitating lien resolution and the option to deal with post-settlement secondary disputes.
What to Do When Family Members (And Even the Lawyers) Are Fighting Over the Settlement Proceeds
Navigating Post-Settlement Complexities with a Qualified Settlement Fund
Great! You have won the case but now face secondary claims and litigation.
No, you are not the first to encounter these issues, and it is not uncommon for post-settlement secondary disputes to occur. For example, families argue over their “Fair Share,” lawyers dispute fee splits, plaintiffs dispute attorney fees, 3rd party lien holders come out of the woodwork to make claims against the litigation proceeds, and more.
Navigating the post-settlement challenges can be overwhelming for lawyers and their clients. But, there is a simple solution - a Qualified Settlement Fund, also referred to as a 468B trust, presents an option to simplify the post-settlement process and handle the hurdles that emerge. By setting up a QSF, the parties can resolve the secondary issues, effectively preserve the settlement funds, ensure tax compliance, and allow time for making informed decisions by deferring taxation.
Here, we delve into the details of QSF and its valuable role in post-settlement planning and administration.
Understanding Qualified Settlement Funds (QSFs)
A Qualified Settlement Fund, sometimes shorthanded as a “QSF,” is an entity created according to IRC Section 468B and its associated regulations to settle various legal disputes. Defendants can place funds into a QSF and receive a release from liability while allowing time for the other parties to resolve secondary disputes and carefully consider their settlement proceeds options.
QSFs trace back to the Tax Reform Act of 1986, which incorporated Section 468B into the Internal Revenue Code. Initially utilized in class action lawsuits, QSFs have since extended to the broad breadth of legal conflicts such as single events, single claimant personal injury claims, and contract breaches.
To establish a QSF, specific requirements must be met:
- Be approved by a “governmental authority” defined by 26 C.F.R. §1.468B-1(c)
- Be under the continuing jurisdiction of the approving governmental authority
- Be set up to resolve one or more legal claims
- Qualify as a trust under applicable state law if established as a trust
PRO TIP: Online QSF platforms like QSF 360 can fully establish a QSF in as little as one business day.
Advantages of Using QSFs for Post-Settlement Resolution
Qualified Settlement Funds offer numerous advantages for all parties involved in post-settlement dispute resolution. By establishing a QSF, defendants can claim immediate tax deductions and extricate themselves from ongoing litigation. At the same time, plaintiffs gain tax deferral, which provides them valuable time to make informed decisions regarding the allocation of settlement funds, aiding in the negotiation of competing claims and liens, and implementation of financial and tax planning strategies.
Avoiding Conflicts of Interest and Ensuring Fair Distribution
Conflicts arise when plaintiffs and their family members are suing each other, and sometimes even when the lawyers get into the act by suing one another or their clients over the allocation of the settlement. Qualified Settlement Funds offer a way to handle these disputes by allowing tax-deferred time to resolve the conflict and preserving the core settlement. The QSF administrator administers the distribution depending on each case’s details and implements the court’s final instructions.
Conclusion
The use of QSFs has transformed how lawyers and their clients navigate the realm of post-settlement disputes and allocation affairs. By offering a streamlined approach to settlement fund management, addressing liens and conflicts, and facilitating settlements, QSFs bring numerous advantages to all parties involved.
By staying up to date, collaborating with experienced QSF professionals, and adapting to the requirements of each case, attorneys and plaintiffs can harness the full potential of QSFs and secure optimal outcomes in the post-settlement stage.
Eastern Point Unveils Comprehensive Guide on Taxable and Tax-Free Settlements
Eastern Point is proud to announce the release of its latest publication, Unveiling the Complex World of Taxable and Tax-Free Settlements.
FOR IMMEDIATE RELEASE
[5/17/2024] — Eastern Point is proud to announce the release of its latest publication, Unveiling the Complex World of Taxable and Tax-Free Settlements. This comprehensive guide delves into the intricate workings of taxable and non-taxable settlements, offering invaluable insights into compensatory damages, punitive damages, and the tax treatment of various settlement types.
Ms. Rachel McCrocklin, Eastern Point’s Chief Trust Officer, commented, “The guide provides a detailed understanding of the pivotal role of IRS Section 104 and the taxability of various settlement types. Our goal is to equip readers with the knowledge to make informed decisions and minimize potential tax liabilities.”
The guide explores strategic methods to minimize tax obligations on settlements, including leveraging structured settlement annuities, Plaintiff Recovery Trusts, and proper allocation in settlement agreements. It is an essential resource for individuals and businesses navigating the complex landscape of settlement taxation.
Arm yourself with knowledge, make informed decisions, and minimize potential tax liabilities with Eastern Point's newest guide.
For more information on Unveiling the Complex World of Taxable and Tax-Free Settlements, please visit https://www.easternpointtrust.com/articles/unveiling-tax-free-settlements-what-you-need-to-know or contact 855-222-7513.
CTRO
PRESS Contact
www.EasternPointTrust.com
info@easternpointtrust.com
Phone: 855-222-7513

Unveiling Tax-Free Settlements: What You Need to Know
What Types of Legal Settlements are Not Taxable?
Settlements and their tax implications can often seem complex for individuals and businesses. It’s essential to grasp the nuances involving taxation of settlements to make informed decisions and reduce tax burdens.
This article dives into the details of taxation of settlements, offering insights into compensatory damages and punitive damages, as well as how different settlement types, like whistleblower settlements, are treated for tax purposes. This article also discusses strategies for minimizing tax responsibilities on settlements and answers common questions such as how to report settlement funds to the IRS and determining the portion of a taxable settlement.
Differentiating Taxable Income From Taxable Settlements
Per Section 61 of the Internal Revenue Code (IRC), all income is generally taxable unless explicitly exempted by another section of the IRC. The taxation of settlements hinges on the nature of the claim and the damages awarded.
Understanding Settlement Taxation
The taxability of settlements is contingent upon “the origin of the claim,” meaning the cause of action that led to the settlement award. Here’s a breakdown illustrating how typical settlements are taxed:

When determining the taxability of a settlement, consider these key factors:
- What was the settlement intended to replace?
- Is there a specific exemption in the tax code that applies?
The Role of IRC Section 104 – Physical Injury
IRC Section 104 excludes certain settlements and awards from taxable income. Specifically, §104(a)(2) of the IRC allows taxpayers to exclude from gross income “the amount of any damages (other than punitive damages) received on account of personal physical injuries or physical sickness.”
However, there are some important nuances to keep in mind:
- The injury must be physical in nature.
- Punitive damages are generally taxable, even if they relate to a physical injury, with a narrow exception for certain wrongful death cases.
Before 1996, Section 104(a)(2) did not have the “physical” requirement. The Small Business Job Protection Act of 1996 changed the code to restrict exclusions for injuries and sickness.
PRO TIP: Emotional distress alone does not qualify for the exclusion under §104(a)(2) unless it originates from a physical injury or sickness.
PRO TIP: Attorney fees that come with damages cannot be deducted by the plaintiff. So, the plaintiff will need to pay taxes on the amount of the award. (Refer to the discussion on strategies in the Plaintiff Recovery Trust to avoid this “double tax” situation.)
PRO TIP: Taxpayers must show that their settlement qualifies for exclusion under Section 104(a)(2). The IRS will review the language in the settlement agreement and legal claims to determine tax treatment. Using precise language in both settlement agreements and court orders can strengthen a taxpayer’s case.
Common Nontaxable Settlements
Settlements stemming from physical injury or illness are generally deemed nontaxable under Internal Revenue Code (IRC) Section 104 (a)(2). These settlements compensate individuals for injuries or sickness. Let’s look at some examples.
Personal Injury Settlements
Settlements received for personal physical injuries are typically nontaxable, including compensation for:
- Dog bites and attacks
- Motor vehicle accidents resulting in physical injury
- Medical malpractice suits based on physical illness or sickness
- Premises liability cases where injury results from property neglect
- Workplace and construction injuries
- Product liability, such as defective medications causing severe harm
The critical factor is that the settlement involves physical injury or sickness. Emotional distress damages originating from a physical injury are also nontaxable.
Medical Expense Reimbursements
When a settlement includes reimbursement for expenses related to the injury, the part of the settlement designated for those expenses is usually not taxable unless those medical expenses were previously deducted by the plaintiff. If, in a prior tax year, the medical expenses were deducted and a tax benefit was provided, then that portion of the settlement may be considered income.

Wrongful Death Settlements
Similarly, settlements for death cases are generally treated as nontaxable since they are handled similarly to injury settlements from a tax perspective. These settlements compensate the surviving family members for reasons including the loss of support, the pain and suffering experienced by the deceased, medical and funeral expenses, and the loss of potential inheritance. However, there are exceptions to consider. Punitive damages in cases of wrongful death are typically subject to taxation. Moreover, any part of the settlement that reimburses expenses previously deducted by the plaintiff may be regarded as income up to the extent of any tax benefits received.
PRO TIP: Contingent attorney fees associated with punitive damages are not deductible to the plaintiff. Accordingly, the plaintiff must pay taxes on the entire amount of the punitive award. (Plaintiff recovery Trust discussion below for strategies to eliminate this “double tax”)
Carefully review the specific circumstances of each settlement to determine the appropriate tax treatment. Consulting with a tax professional can help ensure compliance with IRS regulations.
Common Types of Taxable Settlements
Some settlements are not subject to taxes; however, some require taxation. Let’s delve into some examples of these settlements in detail.
Employment Disputes and Lost Wages
Compensation received for lost wages, back pay, front pay, or severance pay is considered income and is subject to taxes, including Social Security and Medicare taxes (FICA) withholding. Here’s a breakdown of how these settlements are taxed:
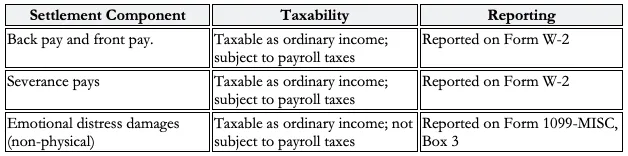
It’s crucial to understand that even if some of the settlement pertains to distress damages stemming from an employment dispute, those damages remain taxable unless they result from an injury or illness.
Punitive Damages
Punitive damages are always taxable regardless of the case’s nature. These damages aim to penalize the defendant for their misconduct and do not serve as compensation for the plaintiff’s losses. Punitive damages are categorized as “Income” on Form 1099 MISC. Are taxed as ordinary income rates.
- Punitive damages are taxable even if the underlying compensatory damages are tax-free, such as in a personal physical injury case.
- The plaintiff must pay taxes on the entire gross amount of punitive damages awarded, including the portion paid to their attorney as a contingency fee.
- Punitive damages are not subject to payroll taxes, as they are not considered wages or compensation.
PRO TIP: Contingent attorney fees associated with punitive damages are not deductible to the plaintiff. Accordingly, the plaintiff must pay taxes on the entire amount of the punitive award. (Plaintiff recovery Trust discussion below for strategies to eliminate this “double tax”)
Emotional Distress Without Physical Injury
When it comes to distress without injury, payments received for mental anguish or emotional distress are usually subject to taxation unless they stem from a personal physical injury or illness. These payments may be tax-free if an injury causes emotional distress. However, these payments become taxable if emotional distress leads to symptoms like headaches or stomachaches.
Let’s consider some examples:
- Emotional distress damages arising from a non-physical injury (e.g., discrimination, defamation) are taxable.
- Emotional distress damages that cause physical symptoms but do not originate from a physical injury are taxable.
- Emotional distress damages that originate from a physical injury or sickness may be tax-free.
When receiving a settlement for emotional distress, it’s crucial to work with a tax professional to determine the appropriate tax treatment based on the specific circumstances of your case.

Whistleblower Taxation
There is no tax exemption exception for False Claims Act whistleblower awards. As such, whistleblowers must pay income taxes on their rewards at the ordinary income tax rates. As such, it remains wise to seek competent advice, as tax questions regarding whistleblower rewards are complex.
PRO TIP: Federal and state income tax burdens apply to qui tam rewards like any other form of ordinary income.
Strategies to Minimize Tax Obligations on Settlements
For those seeking to minimize settlement tax obligations, there are strategies available to reduce the taxes and maximize the recovery for plaintiffs. Utilizing settlement annuities, the Plaintiff Recovery Trust, and proper allocation in settlement agreements can help individuals reduce their tax burden and secure their future.
Structured Settlement Annuities
Structured settlement annuities provide a tax option for recipients of settlements by spreading out the settlement payments over several years instead of receiving a lump sum. This approach helps lower the tax rate. It offers benefits such as tax deferral, guaranteed growth of funds within the annuity, and enhanced financial stability. Regular payments can help secure your future and prevent spending decisions. Different types of annuities offer diverse features:
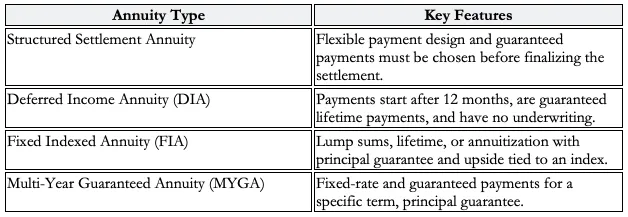
Plaintiff Recovery Trusts
Moreover, Plaintiff Recovery Trusts (PRTs) are tools to avoid taxation for plaintiffs receiving settlements that include attorney fees. By transferring the litigation interest to the trust, plaintiffs only pay taxes on their recovery as beneficiaries, increasing after-tax earnings by 30 to 70%.
PRTs offer additional benefits:
- Increased Premiums: PRTs can increase available structure premiums by 30% in a typical case.
- Simplified Fee Deferral: PRTs eliminate the need to match payment schedules for lawyers’ deferred fees.
- Asset Protection: PRTs can offer increased safeguarding, against creditors by operating as an entity.
Proper Allocation in Settlement Agreements
The tax implications of settlements hinge on the source and nature of the claims involved. By distributing settlement funds in the agreement, plaintiffs can optimize the portion of their recovery exempt from taxes.
- Identify Tax-Free Damages: Allocate funds to claims for personal physical injuries or physical sickness, which are generally tax-exempt under IRC Section 104(a)(2).
- Separate Punitive Damages: Allocate punitive damages separately, as they are always taxable, regardless of the underlying claim.
- Negotiate at Arm’s Length: Ensure allocations result from adversarial, good-faith negotiations to withstand IRS scrutiny.
By strategically employing structured settlement annuities, plaintiff recovery trusts, and proper allocation in settlement agreements, plaintiffs can significantly minimize their tax obligations and maximize their net recovery, providing long-term financial security and peace of mind.

Conclusion
The tax consequences associated with settlements can be complex and diverse, underscoring the importance for individuals and organizations to grasp the intricacies of taxable versus taxable settlements.
Understanding the basics of damages, punitive damages, and how settlements are taxed can help readers make informed decisions to lower their tax burden. Utilizing methods like settlement annuities, plaintiff recovery trusts, and careful allocation in settlement agreements can cut down on taxes. Increase the final amount received. It’s advisable to seek guidance from tax experts and lawyers to handle the intricacies of settlement taxation in line with IRS rules.
Maximizing A Court Award - Strategic Tax Planning for Post-Judgment Interest
Introduction
You prevailed and won the case, and the award includes post-judgment interest – now, taxes are due on the interest.
Unfortunately, many people are taken aback when they find out that post-judgment interest is always taxable in cases involving injuries.
Knowing how this interest is taxed and being ready for it is often overlooked when planning for matters. This discussion focuses on the tax implications of post-judgment interest in physical injury cases and ways to reduce its tax burden.
Is Post-judgment Interest Material?
The notion that post-judgment interest is not material can be fatally flawed. As the appeals process can drag on for years, it is not at all unusual for post-judgment interest to be significant. In today’s courts, cases with millions of dollars in post-judgment interest are not rare.
Pro-Tip: As time passes, tax planning options diminish. Therefore, the time to start planning to mitigate post-judgment interest taxation is before the case is final – the earlier, the better.
Understanding the Taxation of Awards
- Generally, compensation for physical injuries or sickness is non-taxable, including the associated medical bills and lost wages.
- On the other hand, damages for non-physical injuries (such as emotional distress), defamation, and humiliation are ordinarily taxable.
Pro Tip: Taxation of Post Judgement Interest Still Applies Under IRC Section 104. Damages received for injuries or sickness are not taxable gross income under §104(a)(2). However, it’s important to note that this tax exemption does not extend to damages or post-judgment interest. As a result, punitive damages and post-judgment interest are always subject to taxation, irrespective of the type of injury.
Pro Tip: Legal Fees and Deductions.
The 2017 tax law eliminated the deduction for attorney fees linked to awards or settlements. As a result, individuals filing lawsuits now need to include the entire amount of their taxable recoveries as taxable gross income without being able to deduct any legal fees. For more details, click Double Tax.
Tax Planning Strategies for Recipients of Post-Judgment Interest
Utilizing Plaintiff Recovery Trusts
The Plaintiff Recovery Trust (PRT) allows plaintiffs to reduce the tax implications of taxable awards (including post-judgment interest). This specialized trust enables plaintiffs to skip paying taxes on the attorney fee portion of the judgment or settlement, including those linked to judgment interest. As a result, the PRT offers the advantage of helping plaintiffs retain a greater after-tax percentage of the award.
Structured Settlement Annuities and Tax Benefits
Structured settlement annuities, while beneficial, offer less effective strategic tools for plaintiffs to reduce the taxation on post-judgment interest.
Conclusion
Navigating the complexities of post-judgment interest and its tax implications is often an overlooked planning element. The Plaintiff Recovery Trust typically will offer the best taxation outcomes on post-judgment interest awards, and by preplanning to utilize the PRT, recipients can significantly enhance their economic results.
As such, when the possibility exists of court awards with post-judgment interest, one should proactively engage in tax planning strategies EARLY – waiting until after the final award or the appeal is often too late.

The Ultimate Guide to Escrow Accounts for Private Placements
So, you want to conduct a private placement? Whether Reg D, Reg A, Reg A+, Reg CF (Crowdfunding), or Reg S, offering a private placement escrow trust to hold investor funds prior may be required, but it is always a good idea.
Escrow accounts play a vital role in private placement offerings by securely holding investor funds until specific conditions are met, thus offering protection that boosts investor confidence. Opting for a “trust company” over a traditional bank account for escrow purposes introduces the advantage of active independent oversight and more FDIC insurance coverage (up to $150M per account), further enhancing the security and integrity of these escrow transactions.
Using an escrow agent, a neutral third party underscores the commitment to the prudent management of funds in private equity, Reg D, Reg A, Reg A+, Reg CF (Crowdfunding), Reg S offerings, and other private offerings. Another beneficial advantage is that the escrow account increases the confidence of both the offeror and the investor in the outcome. Thus, private placements safeguard investor assets and facilitate smooth transactions with regulatory and private placement offering terms.
Understanding Private Placement Escrow Accounts
Overview of Private Placement Escrow Accounts
Private placement escrow accounts are essential in managing the complexities of private securities transactions. These accounts hold funds raised from investors until the satisfaction of specific offering terms, ensuring compliance with regulatory requirements and safeguarding investor interests.
Steps in the Escrow Process
- Opening an Account: Selecting an escrow agent to establish an account is typically the first step, which can take one to two weeks. However, platforms like Eastern Point Trust Companies can take as little as one business day.
- Securing Financing: The escrow process also involves waiting for the investors’ transmittal of funds, either directly into the escrow or through a broker-dealer, which is critical to proceed with “breaking escrow.”
- Breaking Escrow: Once the terms of the offering have been satisfied, the offeror may request to “break escrow” and begin receiving funds. The escrow trustee will not allow escrow to be broken, and funds will not be available to the offeror until the private placement terms are fulfilled.
Regulatory Framework and Requirements
Private placements operate under the U.S. Securities and Exchange Commission, FINRA, and the associated securities statutes, regulations, and rules, which mandate using a private placement memorandum instead of a prospectus and may restrict marketing to the general public. Specifically, Reg D offerings are only open to accredited investors, adding another layer of complexity. However, Reg A/A+ and Reg CF offerings may be available to non-accredited investors - albeit with other restrictions.
Pro Tip: Always consult with competent legal counsel to safeguard compliance with all pertinent regulations and laws.
The Role of the Escrow Agent
A private placement escrow agent acts as an impartial third party, holding in custody the investor funds securely until all conditions of the private placement offering are met. This role is crucial in “all or nothing” contingency offerings, where the closing (breaking escrow) depends on reaching a stated aggregate amount of funding by a specified date. All funds must be returned to the investors if the minimum is unmet.
Importance of Escrow
Investor funds should be placed in escrow to minimize the risk of violating SEC Rules 10b-9 and 15c2-4.
Selecting the Right Escrow Agent
When choosing an escrow agent, factors such as speed and efficiency, expertise in regulatory compliance, and transparent fund administration should be considered. Thus, utilizing the right private placement escrow agent ensures that the escrow process complies with the statutory requirements of private placements and provides all parties involved the necessary peace of mind.
Advantages of Trust Companies Over Traditional Banks
Opting for a trust company for escrow services in private placements offers the advantage of enhanced independent oversight. Using a licensed fiduciary increases investor confidence and ensures a higher standard of compliance and security in managing substantial financial transactions involved in private equity and private offerings.
Regulatory Requirements for Private Placement Escrow Accounts
Regulatory Frameworks and Compliance
Broker-Dealer Obligations Under SEC and FINRA Rules
Broker-dealers are mandated under SEC Regulation Best Interest (Reg BI) and FINRA Rule 2111 (Suitability) to investigate the security when recommending it thoroughly. By doing so, the broker-dealers ensure they understand the risks and rewards associated with the private placement offerings and have a reasonable basis to believe that the recommendation is in the best interest of retail customers. Thus, the SEC’s Regulation Best Interest (Reg BI) extends to all recommendations to retail customers involving securities transactions or investment strategies, including Reg D, Reg A, Reg A+, Reg CF (Crowdfunding), or Reg S offerings private placement offerings.
Filing Requirements With FINRA
FINRA Rules 5122 and 5123 stipulate that member firms (broker-dealers) must file offering documents and information for private placement offerings they sell with FINRA’s Corporate Financing Department promptly.

Escrow Handling in Contingency Offerings
Rule 15c2-4 Requirements
Rule 15c2-4 governs the handling of funds by broker-dealers during contingency offerings. It mandates that funds must either be placed in escrow with a bank or deposited in a segregated bank account, where the broker-dealer acts as trustee or agent. This rule protects investors by ensuring that offering proceeds are only transferred or under the offeror’s control upon fulfilling the required contingencies.
Selection of Private Placement Escrow Agents
When selecting a private placement escrow agent, choosing an impartial and independent agent with expertise in private placement escrow services is crucial. The escrow agent should use market-accepted agreements and terms and comply with Know Your Client (KYC), anti-money laundering (AML), taxation, and other legal requirements. By doing so, the escrow agent assists in safeguarding that the escrow process complies with all associated statutes and regulations.
Choosing the Right Escrow Agent
Engaging an escrow agent early in the capital raise process is crucial for presenting a well-prepared pitch to potential investors. Proactively selecting your escrow agent while creating the investor presentation can assist in maximizing investor confidence and credibility.
Critical Factors in Choosing an Escrow Agent
- Speed and Efficiency: The chosen escrow agent should have a process for quickly setting up the escrow account. Focus on clearly stipulating the escrow conditions when producing the documents to ensure the timely release of funds once the conditions are satisfied.
- Expertise and Scope: It is essential to select an escrow agent with specific experience in subscription escrow services, private placement compliance, and a deep understanding of industry-specific regulations.
- Optimized Administration: Look for an escrow agent that offers real-time reporting, same-day disbursements, and the flexibility to adapt to changes in the program. These features indicate an optimized administration solution.
- Neutrality and Protection: A corporate escrow agent, being neutral, helps protect the legal rights of all parties involved. Engaging an experienced escrow agent from the onset is pivotal in securing the best outcomes for all parties.
- Experience and Compliance: When selecting an escrow agent, consider their experience, reputation, financial stability, and adherence to regulatory standards. The agent should have robust security measures to safeguard the funds and a process to maintain clear communications with all parties throughout the escrow process.
Conclusion
Selecting the right escrow agent is a pivotal decision in the private placement process. Speed, efficiency, expertise in regulatory compliance, and effective fund administration ensure the escrow process aligns with the applicable regulatory requirements of private placements. The culminating insight from this examination underscores the significance of escrow accounts in providing a secure, regulated structure that supports the intricate dynamics of private placements, fostering a trustful investment environment. This understanding points to further avenues for discussion and research, particularly in optimizing these financial instruments for future transactions and developments within the sector.
The advantages of using a licensed vendor (such as a trust company) over a traditional bank account are measurable. The provision of active independent oversight by a trust company adds a significant layer of security and integrity to these financial transactions, directly contributing to heightened investor confidence.
The crucial aspect of investor confidence is the linchpin in successfully offering private placements. Private Placement Escrow Accounts safeguard investor assets and streamline the “Breaking Escrow” transaction process under the applicable regulatory framework - thus ensuring all party’s satisfaction.
Additionally, you can open an account on platforms like Eastern Point Trust Company.
Never Establish a QSF in Massachusetts – The Unnecessary Taxation of a Qualified Settlement Fund
Massachusetts is known for Boston, Cape Cod, the Salem Witch Trials, and high taxes. It is no surprise that, when creating a Qualified Settlement Fund (“QSF”) in Massachusetts, the state imposes its aggressive tax policy on QSF income. Therefore, any QSFs used in Massachusetts or established by Massachusetts’ governmental authorities are subject to federal and Massachusetts taxation.
Massachusetts’ applicable income tax rate for the 2023 tax year is a flat five percent (5%) rate on the entirety of the QSFs’ taxable income. As of 2023, an additional 4% tax income over $1 million also applies. Thus, the Massachusetts Department of Revenue’s Letter Ruling 08-7 demonstrates that creating a QSF in Massachusetts is a costly mistake that will result in unnecessarily high taxation.

Background of Letter Ruling 08-7
In Letter Ruling 08-7, issued March 28, 2008, the Massachusetts Department of Revenue established Massachusetts’s position concerning the “Taxation of Qualified Settlement Fund.”
The Massachusetts Department of Revenue ruling outlined the following:
- A QSF is subject to tax under the Massachusetts General Laws, Chapter 62.
- The taxation applies if a Massachusetts governmental authority (including a “Massachusetts Court”) establishes a QSF.
- In general, the ruling provides taxation on income derived from or attributable to sources within Massachusetts, including income from tangible or intangible property located or having a situs in Massachusetts and income from any activities carried on in Massachusetts.
- The Massachusetts Department of Revenue asserts that the situs of trust within Massachusetts applies unless the property has formally acquired a situs elsewhere. This doctrine means a QSF (including a designated settlement fund) shall be presumed to be in Massachusetts if the court or the governmental authority that ordered or approved the establishment of the QSF is in Massachusetts or if trust assets or the situs was in Massachusetts for any part of the year.
Conclusion

While a few states have higher taxes than Massachusetts’s top rate of nine percent (9%), many states have no taxation to a trust-based QSF. Thus, planners and attorneys should carefully consider in which jurisdiction you create a QSF and judge the advantages of QSF 360 to tax optimize and reduce your QSF tax liabilities.
You Have Needs,
We Have Expertise
Discover trust and settlement solutions you won’t find anywhere else – thoughtfully designed to protect assets, simplify processes, and deliver peace of mind.
Expert guidance, every step of the way.
Received a check from Eastern Point Trust Company? Call our verification hotline or email our support team to confirm it is authentic before depositing or cashing it.